
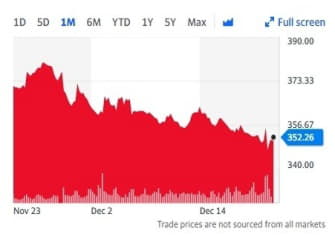
Aerojet Rocketdyne (AJRD) has announced on December 20 that it has agreed to be acquired by Lockheed Martin (LMT) for $56 a share ($51 excluding a special $5 dividend). The transaction, which is to be a $56/share cash transaction, will be reduced by a $5/share special dividend paid to AJRD shareholders prior to the close of the transaction on March 24, 2021. The acquisition is expected to be completed in H2/21. While we are not surprised considering the expected further consolidation in the defense industry, this transaction does raise some regulatory and anti-trust questions. We believe the current regulatory environment is favorable to the transaction, but it remains to be seen if Pentagon officials under the new Biden administration will approve of the transaction, or if any changes can be expected. As of now we do not see a specific reason why the transaction would not be completed, and the acquisition represents a material test for new LMT CEO Taiclet.
The acquisition values AJRD at 13.3x our 2021 EBITDAP estimate of $316M. The acquisition represents a 33% premium to the December 18 closing price of $42.04. Note that AJRD also has ~$5.00/share in net cash. We believe AJRD has seen much of the expected backlog growth (at $6.7B at Q3/20, up ~50% over Q3/19) on its key programs, with the GBSD and next-generation interceptor (NGI) still expected. However, future material margin expansion is unlikely, and the outlook for space and defense is likely to see some shifts under the Biden Administration, which has raised the risk profile for AJRD and some of its key programs. We believe this points to further confidence in space and missile defense markets at large, and the further scarcity of space assets. We believe that the transaction also points to further consolidation in the defense industry as budget growth flattens and funding for development and other investments slows.
Lockheed’s move is seen as highly strategic and an effort to bolster its industrial supplier base and its position on several important programs. AJRD is currently one of Lockheed’s most crucial suppliers, building solid and liquid fuel propulsion systems for virtually all of the prime’s space and defense platforms, including the Orion spacecraft, THAAD, hypersonic missiles, GMLRS rocket artillery and the rocket propulsion for Lockheed’s space launch JV with Boeing, ULA. Through Q3/20, LMT has accounted for ~34% of AJRD’s YTD sales, which is up from 31% over the same period in 2019. The buyout mirrors Northrop Grumman’s acquisition of Orbital-ATK, which locked out other suppliers from the United States’ only supplier of large-diameter solid rocket motors.
Competitors Boeing and Raytheon Technologies are seen as having the most to lose from this deal. AJRD serves as a lynchpin propulsion supplier to virtually all of Boeing and Raytheon’s space and missile programs, including the Space Launch System, Boeing Starliner, hypersonic weapons projects, the Tomahawk cruise missile and the Standard Missile. Additionally, AJRD gives Lockheed a direct role providing propulsion systems on Northrop Grumman’s $85B+ GBSD nuclear missile program. Antitrust concerns and protests by the other primes, especially given the essential solid propulsion monopoly created by Northrop’s acquisition of Orbital-ATK, may yet provide risk to the transaction. After the NOC-Orbital ATC transaction, many believed that AJRD would be acquired by Boeing. However, Boeing does not have the financial flexibility now, in our view, to pose a risk to the AJRD merger with LMT. Lockheed will be hosting a webcast discussing the AJRD transaction on December 21 at 8:30 AM EST.

