
Summary
- Lockheed Martin Q3 results showed why it's a nice name to own during the pandemic.
- Company has guided up for 2020.
- Share price appreciation has been dampened by soft 2021 outlook.
- Pressure on defense budgets is there, but it should be noted that Lockheed Martin tends to guide conservatively.
- Looking for a helping hand in the market? Members of The Aerospace Forum get exclusive ideas and guidance to navigate any climate. Get started today »
Lockheed Martin (LMT) presented its third-quarter results on the 20th of October. In this report, we have a look at the results which I think show why especially during these challenging times Lockheed Martin is a very interesting name to own in the aerospace and defense industry and look at why results have failed to propel stock prices of the defense giant higher.
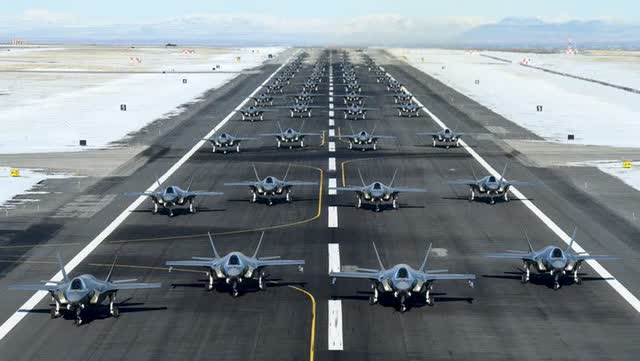
Source: Defense Connect
Revenues Up, Earnings Up, Cash Up

Figure 1: Lockheed Martin Q3 sales and profit (Source: Lockheed Martin)
Starting off with revenues and operating profits, we see the stability of a pure defense business reflected in the year-over-year growth in revenues and profit. Revenues were up 9%, while segment profits went up 6%. Nevertheless, that does mark as light deceleration in year-over-year growth from the previous quarter. So, while the business environment is stable, the pandemic probably has dampened growth a bit as it's hard to shield the entire production system.
Aeronautics sales were up 8% from $6.18B to $6.68B. That marked a deceleration in the year-over-year growth and likely has to do with adjusted work schedules in the third quarter for the F-35 program. Despite the pressure from the adjusted work schedule, there still was growth on stable margins. So, I'm not unhappy with Lockheed Martin’s execution.
The Missiles and Fire Control segment saw sales increase from $2.6B to $2.97B on strong volumes, generating a 16% increase in profits on a 14% increase in revenue. So, we saw nice margin expansion there. Rotary and Mission Systems sales increased 8% to $4B while profits jumped 18% driven by higher volumes and higher margins. Space sales increased 6% to $2.85B but posted lower 20% profits due to lower margins.

