
Summary
- TWOU recently announced 31% growth across all segments for its 3rd quarter 2020 operations.
- The third-quarter results exceeded revenue expectations, which prompted analysts to revise estimates.
- 2U's value proposition is not in the commoditized online learning resources but in the transformational era of quality higher education.
- I do much more than just articles at The Lead-Lag Report: Members get access to model portfolios, regular updates, a chat room, and more. Get started today »
"Great things are not accomplished by those who yield to trends and fads and popular opinion." – Jack Kerouac
Many have been betting on companies that are well-positioned to take advantage of the opportunities brought about by the new normal. But with pharma companies announcing outstanding efficacy results of multiple vaccines under development, many are also forced to tone down ultra-high growth hopes for these companies. One such company is 2U Inc. (TWOU), an education technology platform that provides online degrees, professional certificates, boot camps, and short courses through partner nonprofit colleges and universities. TWOU recently announced 31% growth across all segments for its 3rd quarter 2020 operations. This result continues the 1st and 2nd quarter growth trend, which is 44 and 35 percent, respectively. 2U Co-Founder and CEO Christopher Paucek believes that while COVID-19 has put online education into the spotlight, the need for sustainable, accessible and affordable, blended, relevant, and high-quality online learning will extend far beyond the pandemic. He is also quoted as saying that 2U aims to remove the stigma of online education long term. The company partners with top nonprofit colleges and universities to deliver that promise. Last week, TWOU released its first-ever Transparency Report, aiming to foster greater openness around online education.
Figure 1. TWOU 3-year share price
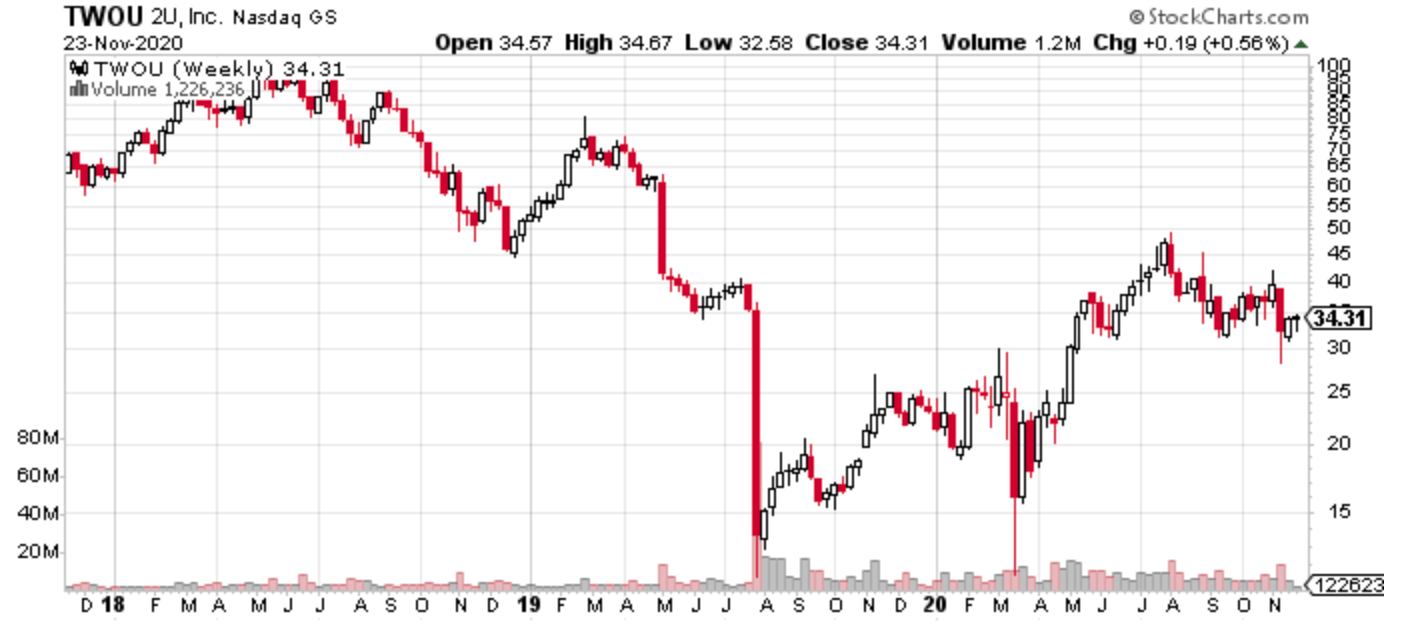
Figure 2. TWOU partner colleges and universities

Source: 2U Inc. Investor Presentation
Financials and Valuation
TWOU's 31% growth was primarily driven by its Alternative Credential Segment revenue, which grew by 57%. The Graduate Program Revenue, on the other hand, increased by 18%. For the full year 2020, the company expects revenue to range from $760 to $775 million, growing within the 32 to 35 percent range. TWOU remains unprofitable, posting a net loss of $9.7 million for the third quarter. Net loss is expected to range from $225 to $210 million for the fiscal year 2020. However, the company managed to bring its 3Q 2020 Adjusted EBITDA into positive territory with the full-year adjusted EBITDA target range of $7 to $14 million.

