
Summary
- 2U posted a strong top and bottom-line performance, continuing to benefit from COVID-19-led shifts in education trends.
- With 2U turning (adjusted) EBITDA positive in F3Q and margin expansion guided in FQ4, FCF breakeven appears to be within reach.
- The undergraduate opportunity adds significantly to the addressable market.
- 2U shares may not be cheap, but I believe the growth outlook justifies the price tag.
- Based on my DCF, I believe the fair value for 2U shares stands at c. $41.
With EdTech increasingly emerging as an exciting new growth area, 2U (TWOU) is in a prime position to benefit as the leading player in the "University Services" segment. As a result of COVID-19, 2U's market opportunity has likely expanded, on the back of the increasing adoption of online graduate degree programs and alternative credentials, along with the longer-term opportunity in the undergraduate space. Valuations remain pricey at current levels, but on the back of continued online learning growth, along with the underlying margin expansion potential, I think there remains an upside in the shares.
Graduate Degree and Alternative Credentials Underpin Top-Line Strength
For FQ3, the company delivered an impressive 31% Y/Y organic growth as demand continued to strengthen across degree programs, short courses, and boot camps. The fact that growth continues to accelerate highlights the increasingly favorable backdrop 2U currently operates across both graduate programs (+18% Y/Y) and alternative credentials (+57% Y/Y).
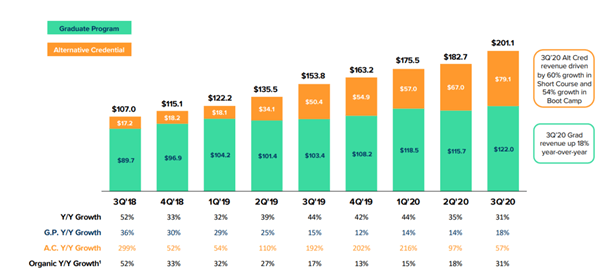
Source: 2U FQ3 Presentation Slides
Graduate program full course equivalent (FCE) enrollment growth of 16.9% Y/Y was a slightly disappointing step down from the 17.8% Y/Y growth in 2Q, while graduate revenue per FCE improved to 0.9% Y/Y growth from a 3.1% Y/Y decline in 2Q due to a greater mix of higher tuition programs. In the alternative credentials segment, revenue increased 56.7% Y/Y, driven by increased demand for short courses. Similarly, alternative credentials FCE enrollment increased 56.6% Y/Y, with alternative credentials revenue per FCE declines also improving to 10.4% Y/Y.
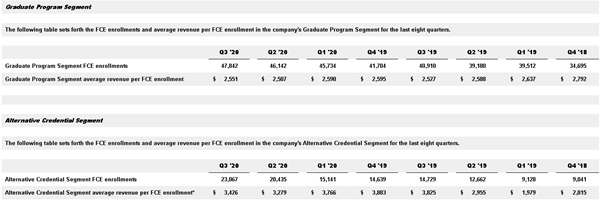
Source: 2U FQ3 News Release
With the demand tailwind in the alternative credentials segment mainly coming from an increasing need to upskill and reskill via distance learning to improve career prospects amid COVID-19, I see plenty of room for growth ahead. Meanwhile, the graduate degree side has seen relatively slower growth but provides investors with greater visibility and resilience, considering the average program length of c. 2.5 years.

