
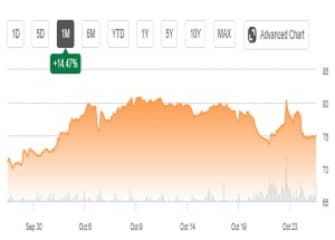
Capital One (COF) has handily topped expectations in the third quarter. While analysts expected revenues to drop 3.5% YOY, the consumer bank delivered the widest top-line beat of the past five years, at least. Driven by higher revenues, especially on the non-interest side and a release of credit reserves, non-GAAP EPS of $5.05 also caught Wall Street by surprise.
But the headline numbers, as good as they were, do not give me the necessary confidence to bet heavily on the consumer banking space. In my view, the combination of (1) lower spending and consumer leveraging, (2) a potential deterioration in credit driven by the COVID-19 crisis and lack of further government stimulus, and (3) unfavorable interest rate environment conspire against Capital One and its direct peers in the foreseeable future.
READ FULL ARTICLE HERE

