
Summary
- Lockheed Martin posted strong results enabled by prudent mitigation measures taken.
- Strong results reflect top-line growth on stable margins.
- Company has guided up for the remainder of 2020, which is a strong sign.
- Looking for a helping hand in the market? Members of The Aerospace Forum get exclusive ideas and guidance to navigate any climate. Get started today »
Lockheed Martin (LMT) presented its second-quarter results on the 21st of July. In this report, we have a look at the results which I think show why especially during these challenging times Lockheed Martin is a very interesting name to own in the aerospace and defense industry.
Source: MarTech Series
Revenues Up, Earnings Up, Cash Up
Source: Lockheed Martin
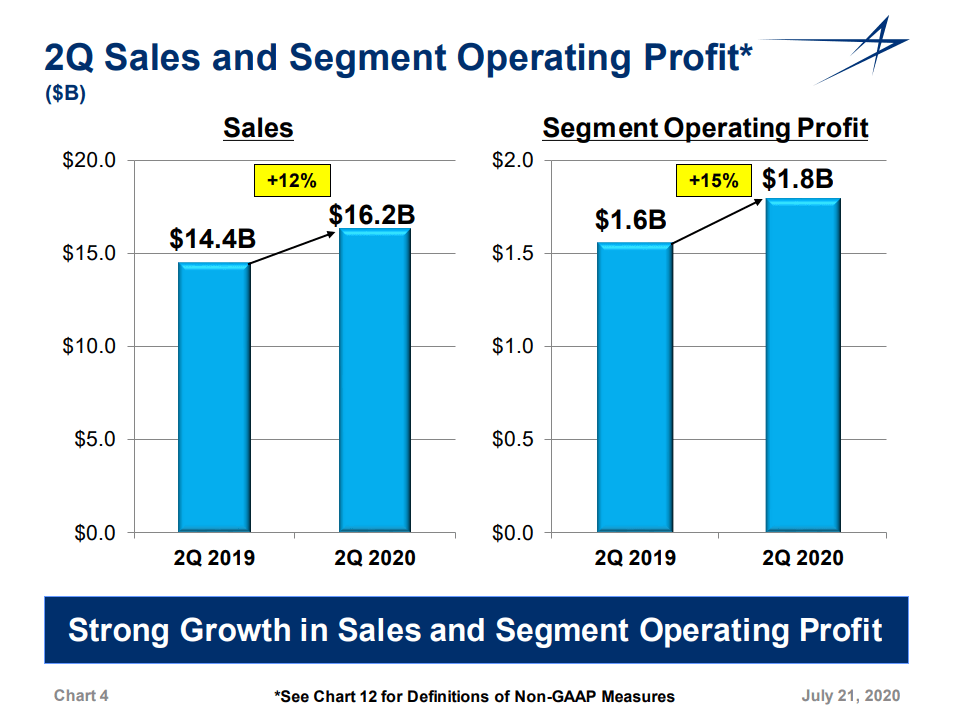
Starting off with revenues and operating profits, we already see two things we are liking about Lockheed Martin. The first one is that while many companies are seeing COVID-19 driven declines, Lockheed Martin sales were up 12%. The second thing we like about the presented results is that while sales increased by 12%, there was a 15% increase in operating profits. So, there is a nice margin expansion there.
Aeronautics sales were up 17% from $5.55B to $6.5B and that really reflects that Lockheed Martin has done a very good job shielding production from any COVID-19 disruptions. Year over year, we saw F-35 deliveries decline by 4 units and C-130J deliveries by 3 units. Given COVID-19 supply chain and logistics challenges, I think that is not too bad, and if you couple that to the 17% increase in sales and 25% increase in profits, that is actually great.
The Missiles and Fire Control segment saw sales increase from $2.4B to $2.8B on strong volumes, generating a 13% increase in profits on a 16% increase in revenue. So, there was some margin contraction there, but given that this is a high-volume business segment, that was to be expected due to the pandemic. Rotary and Mission Systems sales increased 7% to $4B while profits jumped 24% driven by higher volumes and higher margins. Space sales increased 7% to $2.9B but posted lower 13% profits due to lower margins.
All that led to a 15% jump in profits showing that so far, Lockheed Martin has been able to limit the COVID-19 impact on its production and, of course, the demand for their product portfolio is reflected as well. During the quarter, Lockheed Martin announced a $128 million charge, moderating the 22% growth in earnings per share to 16%. The non-cash charge was recognized as Lockheed Martin and Sikorsky sold their 40% stake to Abu Dhabi based EDGE.
Translating all of that to cash level, cash from operations rose 30% to $2.1B. That, however, is not fully reflective of strong core performance as it includes various cash preserving measures under the CARES Act and accelerated receipts. Absent these elements, the increase in cash from operations would be around 20%, in line with the EPS growth.

