
Summary
- Data center REITs are strong, but expensive.
- Much of their value comes from their acquisition/development pipelines.
- IRM's pipeline in the data center space is vast and it is not yet priced into the stock. We see significant upside to fair value.
- This idea was discussed in more depth with members of my private investing community, Retirement Income Solutions. Get started today »
The Buy Thesis
In a sum-of-the-parts valuation, we believe Iron Mountain (IRM) is clearly worth more than its market price. Its 3 main segments are:
- Records Information Management or RIM
- Data Centers
- Data Center growth pipeline
I understand that it is unusual to ascribe value to a pipeline, but we will detail why this has discernable value. The market seems to be valuing IRM exclusively on its RIM business with the rest getting overlooked.
Confusion discount
The data security REIT has not been able to get the market's attention when it comes to their data center business. As presented, their data center revenues get lost in the sea of storage revenues and the market is simply not giving IRM credit for either its current data center profitability or its substantial pipeline in the space. Part of the issue is the way IRM labels its revenues into just 2 buckets; storage rental and service.
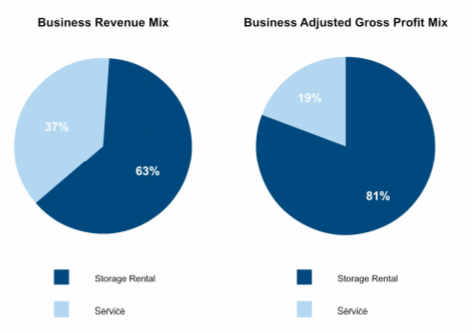
Source: IRM 4Q19
Within the legacy RIM business, storage rental refers to the revenues they get from storing boxes on behalf of their clients and service revenue is stuff like document shredding and physical to digital conversions.
Oddly, IRM uses the exact same labels (storage rental and service) to describe their data center business. Thus, the data center revenues just get lost in the mix.
I believe this is evident in IRM's multiple
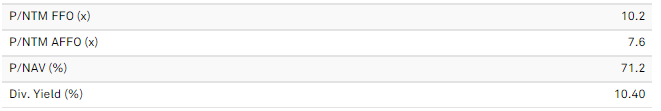
Most of the data centers trade around 20X FFO.
So, to cut through the amalgamation that is IRM's presentation of its revenues we are valuing each part individually.
What is RIM worth?
Well we know the revenue of RIM to be $3.812B annually and the EBITDA to be $1.563B.
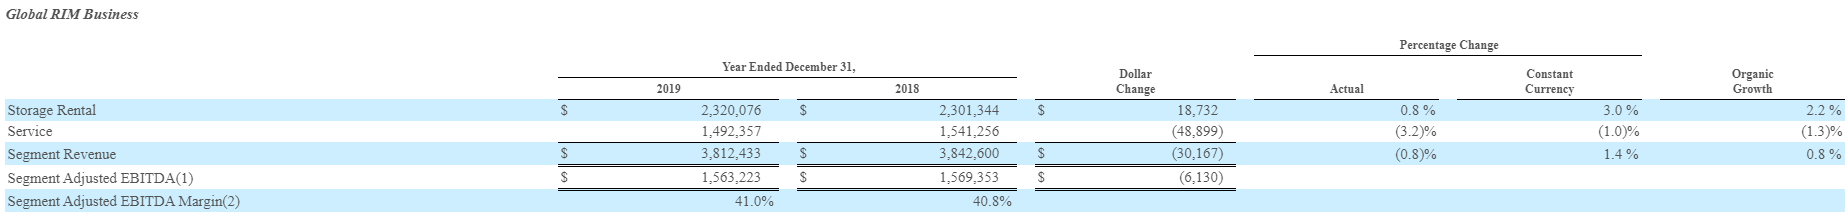 Source: IRM
So the question is, what multiple should be applied to this?
Of the 181 REITs, 177 clearly report enterprise value and EBITDA in their filings. Among these 177, the median EV/EBITDA is 13.8X and the mean is 15.7X (data aggregated from SNL Financial).
Contributing factors to a higher multiple are
- Growth
- Margin
- Capex intensity
IRM's RIM business looks reasonably good in each of these factors.
Organic growth is not rapid, but consistently positive.
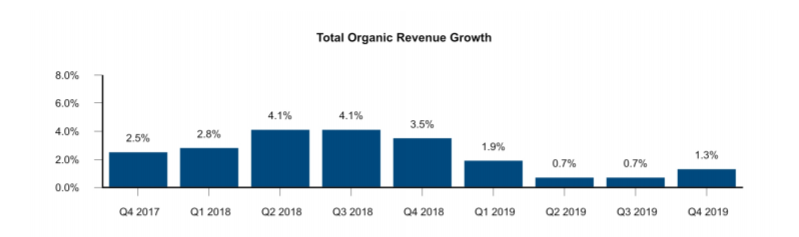 Source: IRM
At 41%, margins are healthy and capex is reasonably low as storage facilities don't require all that much dressing up. IRM's main capex is its fleet of trucks that transport documents to and from their facilities.
Bears, however, would argue that the growth is going to turn negative due to a secular trend toward digitization and away from physical documents. IRM is partially insulated from this trend as they actively profit from physical to digital conversions, but it is a slight risk to volume. Another insulating factor is that while growth has substantially slowed in the U.S. it has held strong internationally.

