
Summary
- A strong late-2020 Marriott price recovery has already "discounted" a normalized hotel sector economy by the summer of 2021.
- However, excessive leverage leaves little room for forecasting and business execution error.
- Weakening technical momentum in many underlying indicators seems to be screaming the equity advance is overdone.
Would you want a company with $25 billion in total liabilities, including $10 billion in debt, that may or may not earn a maximum $1 billion in GAAP profits next year? Free cash flow is forecasted at $1.5 billion, if everything runs smoothly, and the balance sheet is holding $3.5 billion in current assets like cash and receivables. Basically, it's the same fundamental earnings picture as a decade ago. By the way, you are paying $42 billion for the business, and the dividend was cut to zero early in the year.
 Image Source: Domes of Elounda, Greece - Marriott Website
I am explaining the overleveraged setup of Marriott International (MAR). One of the world's leading hotel chains has witnessed a near complete recovery in its stock quote to $129 a share, far from the coronavirus panic low in March under $50. Investors have bid up the company as if operating results will be back to normal by the summer, no harm, no foul, from the pandemic collapse in travel and vacation spending. Is this a realistic assumption, or proof that a central bank, money printing-induced bubble in investor thinking has taken over Wall Street?
Image Source: Anaheim Residence Inn - Marriott Website
Clearly, an investment in Marriott requires a lot of questions to be answered in the affirmative, with hope and blind faith laying the foundation for your buy decision. In the end, I will pass on the proposition. Plenty of variables may not play out as currently forecasted by optimists, and too much financial leverage leaves little room for error.
Extreme Valuation and Financial Leverage
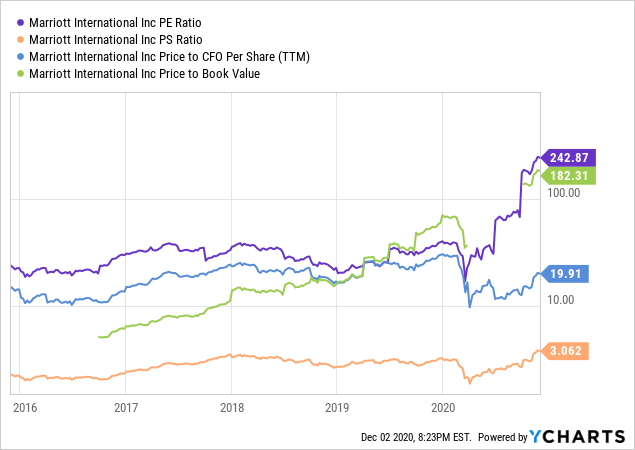
Today's valuation, as you would expect in the middle of the pandemic, is the worst on trailing results EVER. Below is a 10-year picture of the 2020 disaster for operating results. Price-to-backwards-looking earnings, sales, cash flow and book value describe a scary, even ugly investment proposition.
Total returns, including dividends, have been relatively average vs. peers the last three years. I have drawn the competitor group of Hilton Worldwide (HLT), Host Hotels (HST), Hyatt Hotels (H), Choice Hotels (CHH) and InterContinental Hotels PLC (IHG) for industrywide comparisons. I have also included the S&P 500 index to contrast to the group.

