
Summary
- Omega Healthcare Investors was gaining significant momentum in terms of both its stock price and operational performance. It collected 99% of rent in Q2.
- Up over 200% from March lows, Omega has been a solid pick for WER and iREIT. Fears regarding healthcare facilities legal exposure and tenant retention drove the initial weakness.
- Despite reporting a significantly better-than-expected Q2 compared to the street's estimates, the firm reported results in line with WER's expectations.
- On its way back toward $40 per share from the $13.33 March low, Omega has hit a significant snag. Tenant issues have caused a $140 million write-down.
- Let's examine the thesis behind our positive recommendation in March/April, the impact of recently announced tenant issues, and update our valuation.
- This idea was discussed in more depth with members of my private investing community, iREIT on Alpha. Get started today »
This article was coproduced with Williams Equity Research:
Almost four years ago, the day after election day (November 9, 2016), I published an article titled The Trump Factor: A Blue Chip REIT On Sale in which I explained,
"...we have nominated a new president and it's highly likely that the financial markets will become overly cautious. I am expecting to see a broad selloff and that means I can tell you about a cheap "sleep well at night" REIT that may become even cheaper today."
At the time, shares in Omega Healthcare Investors (OHI) were trading at $30.46 per share with a dividend yield of 8.0%. In the same article I explained,
"Keep in mind that a market downturn is the true test of an investment philosophy. Securities that have performed well in a strong market are usually those for which investors have had the highest expectations. When these expectations are not realized, the securities, which typically have no margin of safety, can plummet."
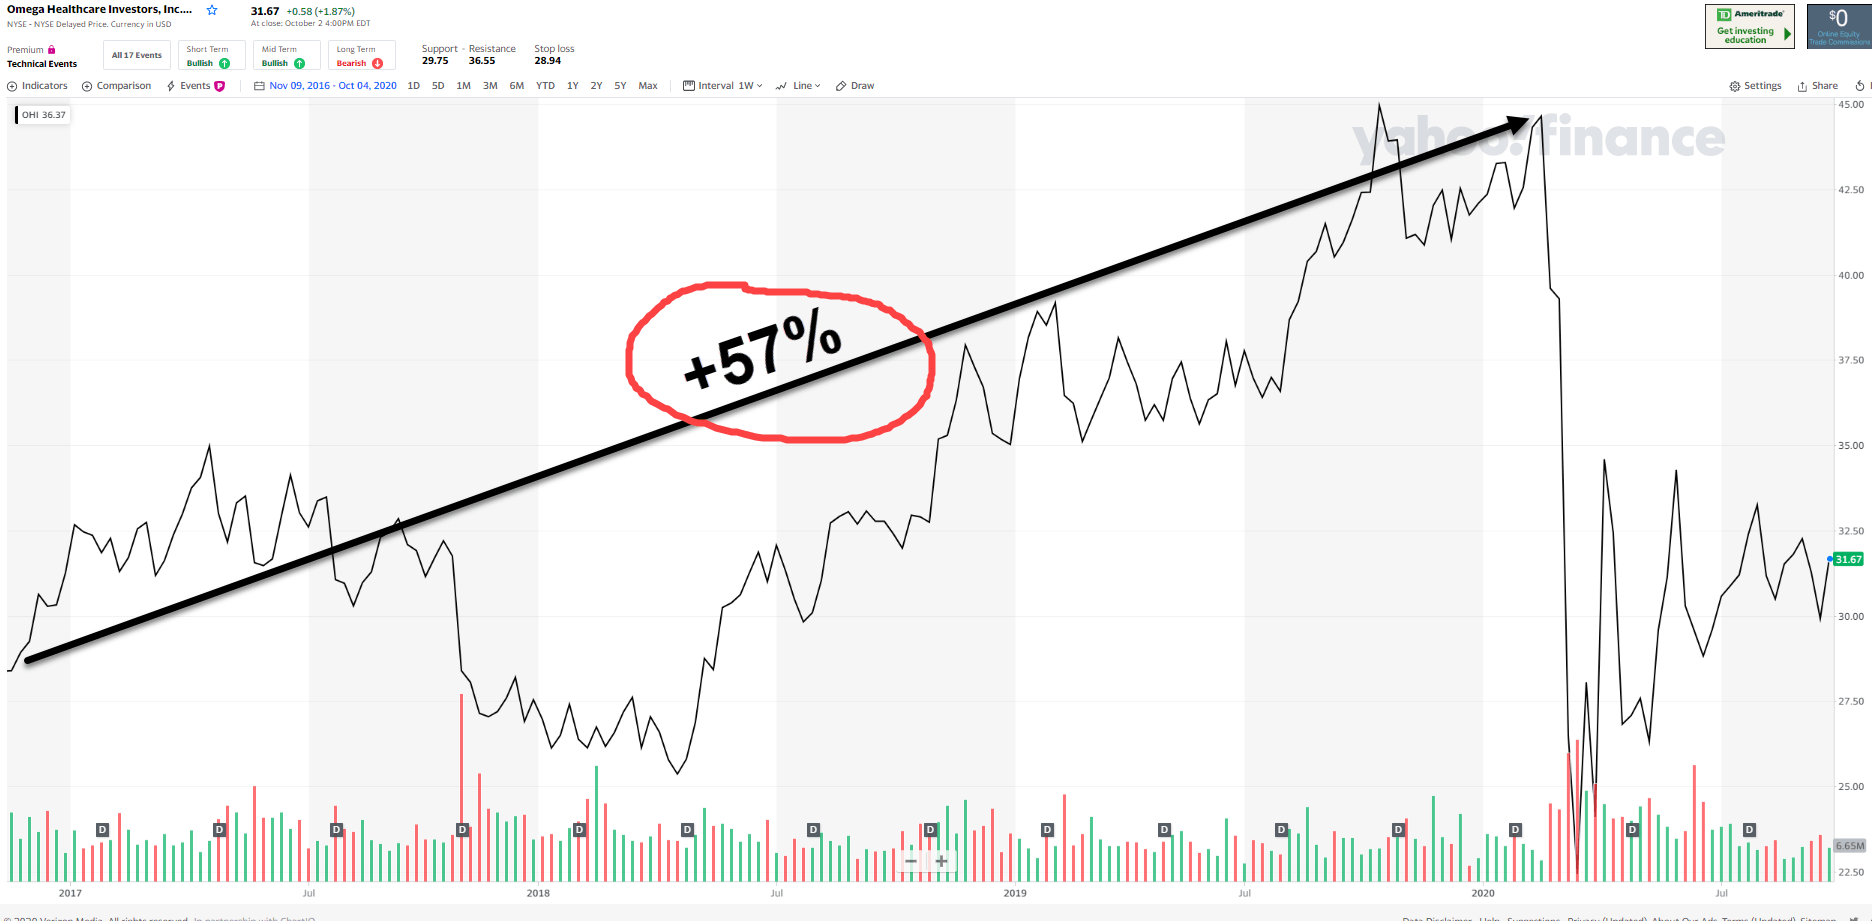
Source: Yahoo Finance
Now, as you can see (above), Omega was up 57% prior to the pandemic, and we had recommended a Hold based on valuation. In fact, we have been buying Omega since 2013 for the Durable Income Portfolio, and this position has returned an average of 13.8% annually since that time. Omega represents just over 3% of the Durable Income Portfolio.
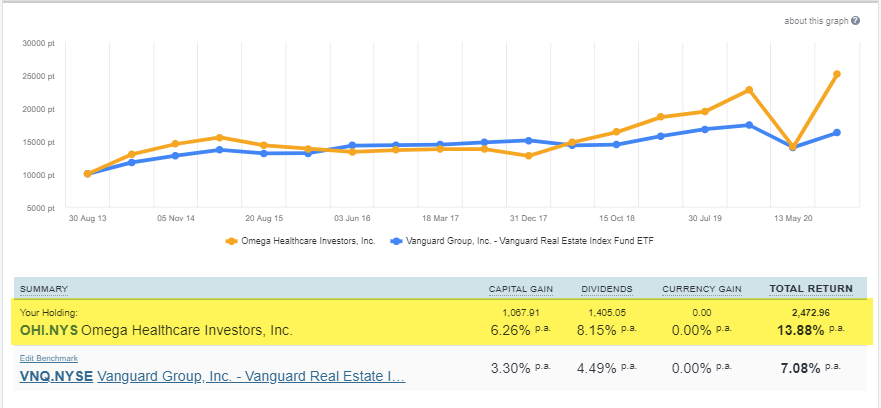
Source: Sharesight
Now, because of the pandemic, Omega is trading within our strike zone, and we have decided that it was time to provide readers with a deeper dive research report. Williams Equity Research (“WER”) last discussed Omega in his August 8th Earnings Analysis. Key sections are provided below.

